A budget management site is structured around specialized sections: expense tracking, forecasts, account management, data security. Each section serves a specific function in financial management. Understanding this architecture allows users to leverage each tool to its full potential, without wasting time searching for the right feature.
Read-only access and PSD2 framework: what it means to connect your bank accounts
Bank connection in a budgeting application relies on a mechanism regulated by the European directive PSD2 (Payment Services Directive 2). This framework distinguishes two levels of access: account information and payment initiation.
Budget tracking tools operate in “read-only” mode. They retrieve balances and transactions, but cannot move money or make transfers. This separation protects the user from any risk of fund manipulation by a third party.
The connection is made through regulated providers, such as Ponto (Isabel Group), which provide access to banks across several European countries. This is where multi-bank coverage becomes a selection criterion: an application capable of reading accounts from multiple institutions in different countries offers a consolidated view that manual CSV statements do not allow.
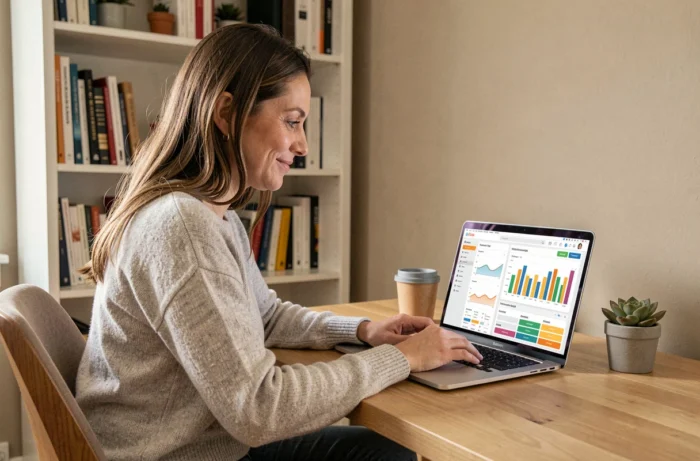
By browsing the sections of the My Budget View site, one can quickly identify which sections deal with bank connection and which manage categorization or forecasting, two distinct functions that are often confused.
Automatic categorization of transactions: the section that saves time
Importing transactions is not enough. Each transaction must be linked to a category (food, housing, transport, leisure) for tracking to make sense. The automatic categorization by keywords analyzes the description of each bank line and assigns it a category without manual intervention.
The time savings are direct: instead of sorting through hundreds of lines each month, the user only corrects misattributions. High-performing applications also allow for the creation of custom rules, for example, forcing the assignment of any payment containing “Carrefour” to the food category.
What differentiates a good categorization section
- The ability to create subcategories tailored to one’s own lifestyle, not just generic labels imposed by the software
- A learning mechanism that retains manual corrections and applies them to future imports
- Displaying uncategorized transactions in a dedicated queue, to ensure nothing is overlooked
This section forms the foundation of the budget. Without reliable categorization, expense graphs and forecasts are based on false data.
Budget forecasts and debt management: anticipating rather than suffering
A budget forecasting section calculates the future balance by projecting recurring income and planned expenses over the coming weeks or months. The goal is to identify an overdraft before it occurs, not after.
Some sections also include a debt planning module. The principle: enter the borrowed amount, the rate, and the duration, then visualize the impact of repayments on cash flow month by month. This tool is particularly useful for deciding between early repayment of a loan or maintaining a liquidity reserve.
PSD2 reconnections and multi-bank portability
A point rarely addressed by budgeting applications concerns the periodic reconnection required by PSD2. The consent to access bank data expires regularly, requiring the user to revalidate the connection with their bank.
Applications that handle this process poorly create gaps in the transaction history. Some months appear incomplete, which skews forecasts. A good budgeting tool notifies the user ahead of the consent expiration and re-establishes the connection without data loss.
Multi-bank portability goes further. Changing banks should not require reconfiguring the entire budget. A well-designed application retains the categorized history even when the source account is replaced by a new one, in another bank or another European country.
Financial data security: encryption and two-factor authentication
The security section of a budgeting site covers two distinct areas. The first concerns the end-to-end encryption of stored data: financial information is rendered unreadable to anyone without the decryption key, including the application publisher.
The second pertains to authentication. Two-factor authentication (2FA) adds a layer of verification during login, typically via a temporary code sent by SMS or generated by a third-party application.
- Encryption protects data at rest (stored on the server) and in transit (exchanged between the browser and the server)
- 2FA prevents a third party from accessing the account even if they know the password
- Regulated banking aggregation providers are themselves subject to compliance audits imposed by financial regulators
Checking for the presence of these two mechanisms in the dedicated section of a budgeting site is a basic reflex before entrusting one’s banking credentials.
A methodical reading of each section of a site like My Budget View allows users to understand exactly what data is collected, how it is processed, and what technical limits apply. It is this structural transparency, section by section, that distinguishes a reliable tool from an opaque application where features are stacked without visible logic.